How Does a Fire Damage Claim Adjuster in Massachusetts Handle Complex Property Claims?
October 13, 2026When Should You Hire a Fire Damage Claim Adjuster in Massachusetts After a Fire?
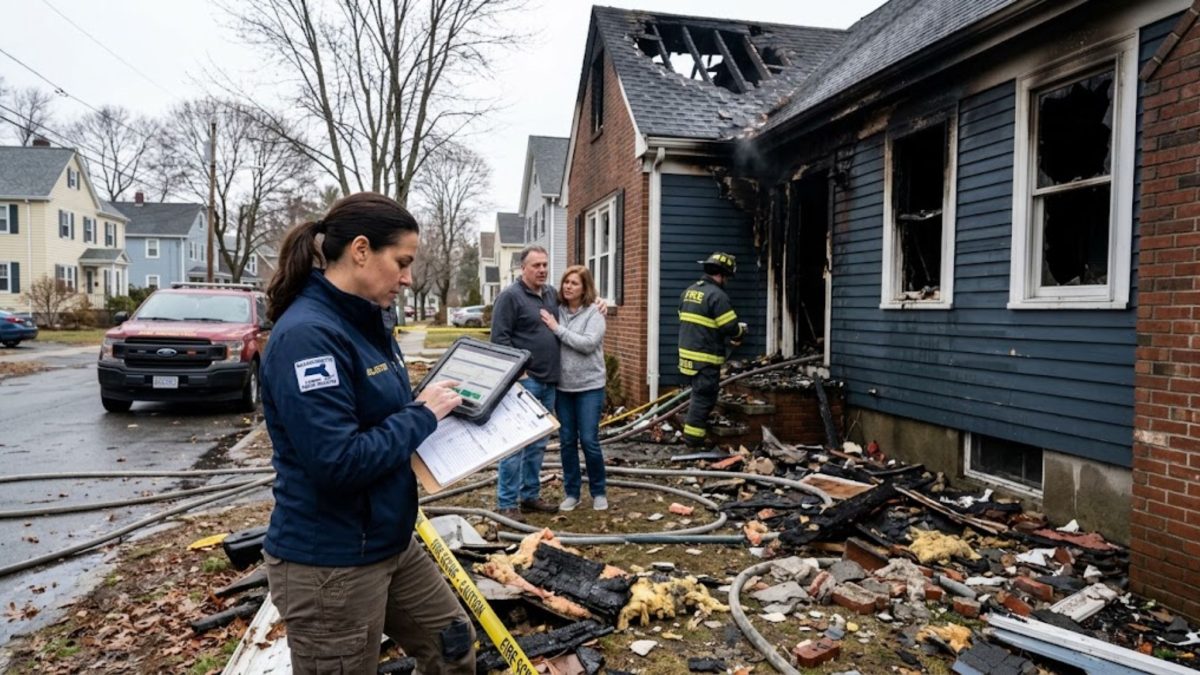
Standing amidst the lingering smell of smoke and the devastating remnants of a residential or commercial blaze leaves property owners feeling utterly overwhelmed, yet the timeline for protecting your financial future begins the very moment the flames are extinguished. When property disasters strike the Bay State, navigating the intricate nuances of an insurance policy requires specialized advocacy, which is precisely why engaging a fire damage claim adjuster Massachusetts early in the process changes the trajectory of your recovery. Insurance carriers deploy their own adjusters whose primary loyalty remains tied to corporate profitability, meaning policyholders frequently encounter suppressed settlement offers that fail to cover full structural restoration. By partnering with dedicated professionals who understand local building codes, municipal regulations, and policyholder rights, you level the playing field against corporate adjusters. Understanding the precise window for intervention ensures that critical evidence is preserved, inventories are documented thoroughly, and negotiations yield the equitable payout necessary to rebuild your life.
When Is the Ideal Time to Involve a Professional After a Fire?
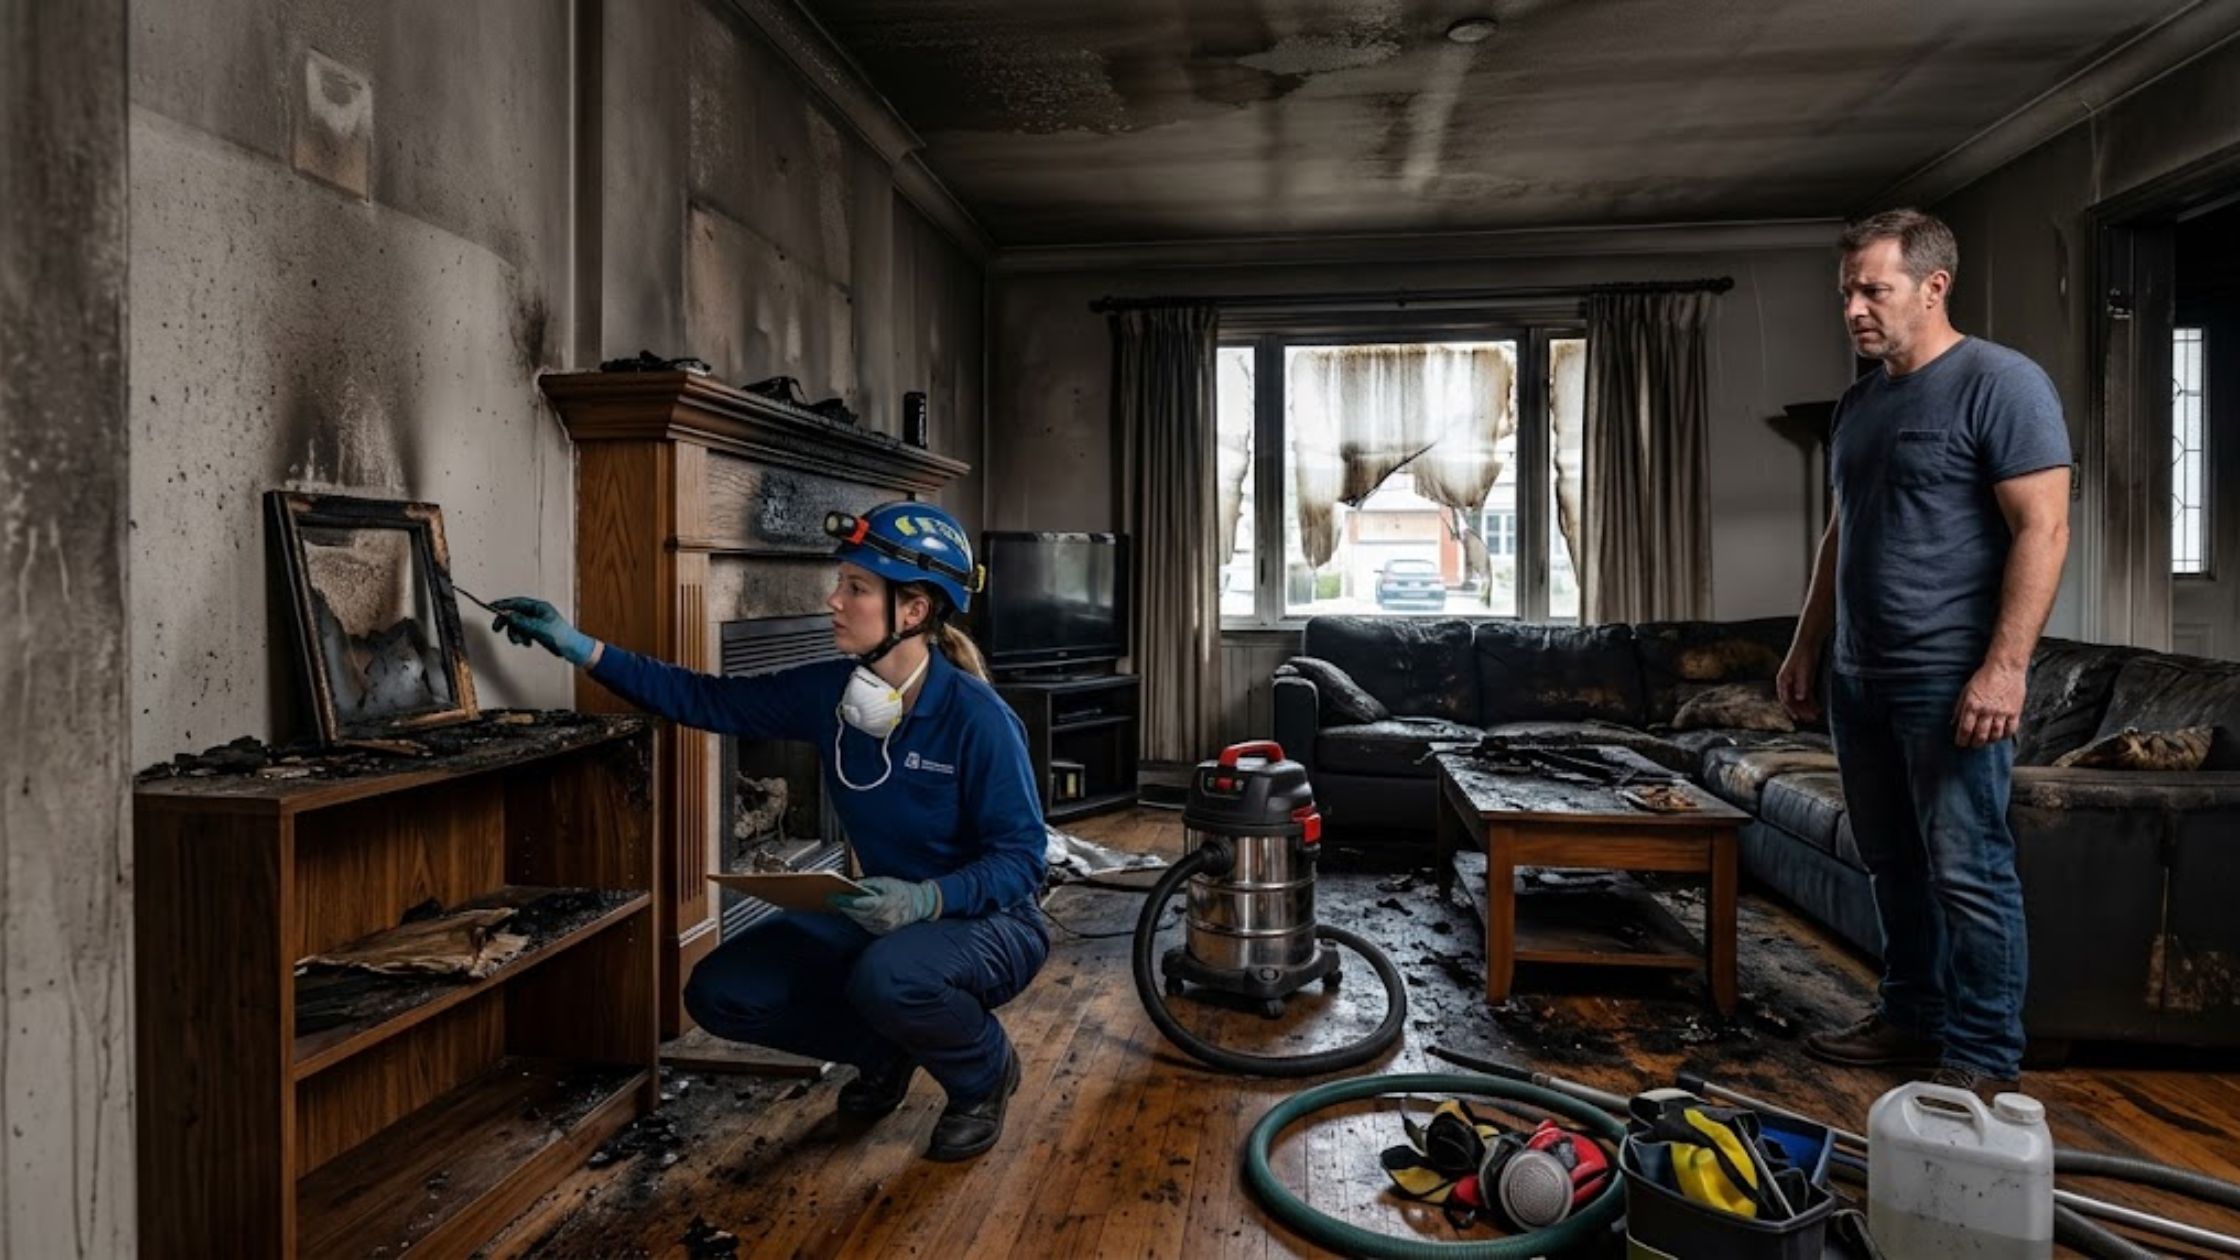
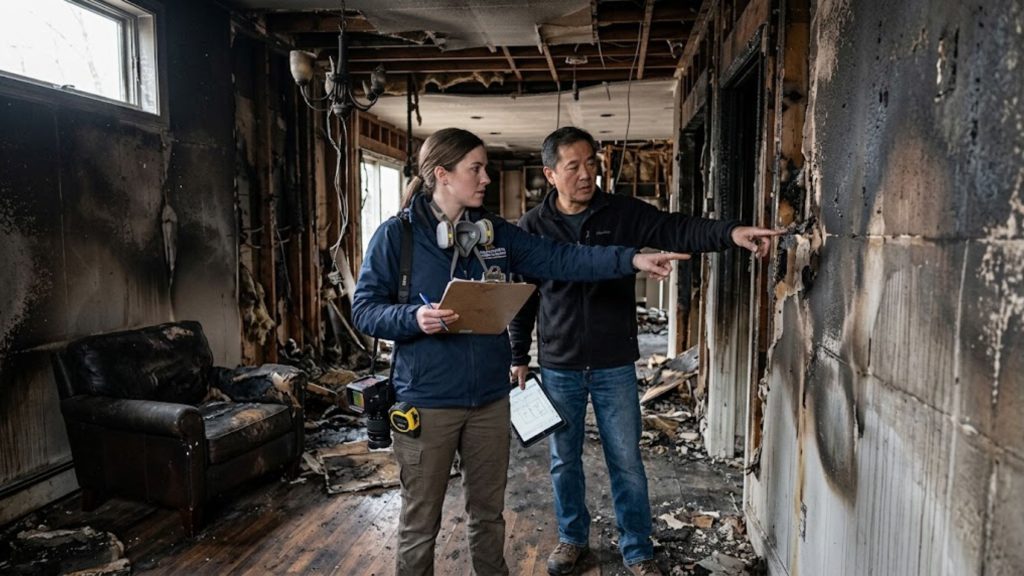
The optimal moment to bring in professional representation is immediately after the fire department departs and safety is established, long before you provide a formal recorded statement to your insurance carrier. Many property owners make the critical mistake of waiting weeks for the insurance company’s adjuster to complete an initial inspection, losing valuable time and vital evidence in the process. Early involvement allows your advocate to document hidden structural damage, soot migration, and water intrusion caused by firefighting efforts before cleanup crews alter the scene. Insurance policies contain strict duties after loss provisions that require policyholders to prevent further damage and provide meticulous proof of loss statements within compressed deadlines. Having an expert guide these initial steps prevents accidental misstatements that carriers routinely use to devalue or deny legitimate claims. Engaging a qualified specialist right away ensures that every aspect of the disaster is recorded accurately from day one.
How Do Insurance Companies Handle Major Property Losses?
Property insurers operate as large commercial enterprises designed to manage payouts efficiently while protecting their financial bottom line. When a major loss occurs, the insurance company assigns an adjuster whose core mandate is to investigate the claim through the lens of policy limitations and exclusions. These carrier representatives routinely overlook hidden damages behind walls, undervalue specialized restoration labor, and apply aggressive depreciation formulas to personal belongings. Property owners often assume that the carrier’s estimate represents a fair and final assessment of the damage, unaware that complex policy terminology leaves room for interpretation. Without independent expertise, policyholders struggle to challenge low settlement offers or prove the true cost of modern construction materials and labor standards. Recognizing how insurance adjusters evaluate losses highlights the absolute necessity of retaining independent advocacy to protect your financial interests.
What Are the Core Benefits of Working With Independent Adjusting Experts?
Retaining professional assistance transforms a stressful, one-sided administrative ordeal into a structured, highly organized negotiation backed by verifiable industry data. Independent advocates specialize in dissecting complex policy language, ensuring that coverage limits for dwelling protection, personal property, and loss of use are maximized. They utilize advanced estimating software that mirrors the exact pricing models used by major insurers, eliminating discrepancies in material and labor costs. Furthermore, handling communications through a dedicated professional shields traumatized property owners from aggressive questioning and bureaucratic delays. This hands-on guidance allows families and business owners to focus entirely on emotional recovery and temporary housing while experts manage the heavy lifting of claim preparation.
|
Claim Stage |
Insurance Carrier Focus |
Policyholder Advocate Focus |
|
Initial Inspection |
Identifying policy limits and exclusions |
Documenting all visible and hidden structural damage |
|
Scope Preparation |
Generating minimum repair estimates |
Creating comprehensive line-item restoration budgets |
|
Inventory Listing |
Demanding basic itemized receipts |
Recovering lost items through detailed memory triggers |
|
Final Negotiation |
Minimizing total payout exposure |
Maximizing equitable recovery under policy terms |
Why Is Immediate Documentation Critical for Your Property Claim?
The days immediately following a disaster represent a critical window where physical evidence of structural compromise and personal property destruction is most pristine. Insurance policies place the absolute burden of proof squarely on the policyholder, meaning vague descriptions or missing receipts result in automatic claim reductions. Professional specialists conduct exhaustive walkthroughs, utilizing high-resolution photography, thermal imaging, and moisture meters to capture every square foot of impacted space. This meticulous documentation forms an unassailable foundation when compiling the mandatory proof of loss statement required by your carrier. Failing to record this evidence before emergency mitigation or debris removal begins can permanently eliminate your ability to claim vital repair funds. Thorough preparation safeguards your financial investment and prevents insurers from disputing the origin and severity of the loss.
How Do Complex Building Codes Impact Your Restoration Budget?
Restoring a fire-damaged property in New England involves far more than simply replacing burned lumber and repainting soot-stained walls. Local municipal building departments enforce stringent current building codes that frequently require structural upgrades, updated electrical wiring, and enhanced insulation during repairs. Many standard insurance policies include ordinance or law coverage, yet carrier adjusters routinely omit these mandatory municipal expenses from their initial settlement calculations. Independent advocates audit local zoning requirements and building mandates to ensure that every code compliance cost is fully integrated into the claim payout. Ignoring these regulatory requirements leaves property owners facing thousands of dollars in out-of-pocket expenses when contractors pull required municipal permits. Ensuring your settlement accounts for code updates guarantees a safe, legally compliant, and fully restored building structure.
What Steps Define the Comprehensive Claims Lifecycle?
Navigating a major property insurance claim requires a systematic, multi-phase approach that moves steadily from immediate emergency stabilization to final financial recovery. Each phase presents unique administrative hurdles and communication requirements that demand careful attention to detail and adherence to strict contractual deadlines.
Emergency Stabilization and Safety Mitigation
The immediate aftermath of a fire requires rapid coordination of emergency board-up services, roof tarping, and environmental stabilization to prevent secondary weather damage. Professional teams secure the perimeter against unauthorized entry while initiating specialized soot removal and water extraction protocols. Quick action during this phase minimizes long-term corrosion and mold growth, preserving the structural integrity of the remaining building materials.
Detailed Scope and Damage Estimation
Once the property is stabilized, specialists conduct a comprehensive evaluation to draft an exhaustive, line-item estimate for all necessary repairs. This process involves measuring square footage, assessing HVAC contamination, and cataloging every damaged architectural feature. Presenting a detailed, verifiable scope prevents insurers from utilizing generalized, low-ball depreciation software during negotiations.
Comprehensive Personal Property Inventory
Cataloging destroyed or smoke-damaged personal belongings is often the most tedious and emotionally draining aspect of recovering from a residential fire. Experts assist clients in reconstructing exhaustive room-by-room inventories, noting brand names, purchase dates, and replacement values for every item lost. Thorough inventory preparation ensures that policyholders collect the full value of their personal property coverage limits.
Direct Negotiation and Settlement Resolution
The final phase involves formal presentations of the compiled claim package to the insurance company’s management and adjusters. Experienced negotiators lead all discussions, defending every line item against carrier pushback and resolving disputes regarding depreciation or scope omissions. This persistent advocacy secures a maximum equitable settlement without requiring the stress of litigation.
|
Project Phase |
Primary Action Required | Key Objective |
|
Phase 1 |
Emergency board-up and water extraction |
Prevent secondary property deterioration |
|
Phase 2 |
Comprehensive structural damage auditing |
Establish accurate baseline repair costs |
|
Phase 3 |
Room-by-room personal property inventory |
Maximize content replacement recovery |
|
Phase 4 |
Carrier negotiation and final settlement |
Secure full and fair financial payout |
How Does Marinilli Associates Advocate Exclusively for Policyholders?
When disaster strikes your home or commercial enterprise, having a trusted partner who represents your interests rather than corporate profits makes all the difference. Marinilli Associates brings decades of hands-on experience in navigating complex property losses across New England. Our licensed professionals understand how to counter insurance company tactics through rigorous documentation and expert negotiation strategies. You can learn more about our foundational mission and client commitment by visiting our about us page to see how we stand shoulder-to-shoulder with policyholders. We operate on a contingency fee structure, meaning our compensation is strictly tied to increasing your recovery, ensuring zero upfront financial risk for your family or business.
Why Should You Never Accept the First Settlement Offer?
Insurance carriers frequently issue quick initial settlement checks designed to provide immediate relief while closing claims swiftly and cheaply. Accepting these preliminary offers usually releases the insurance company from any future liability, preventing you from claiming additional funds when hidden damage is discovered later. Hidden smoke infiltration within wall cavities, structural warping, and electrical system compromises often remain undetected during casual inspections. Experienced advocates review these initial proposals critically, identifying glaring omissions and undervalued repair line items that require immediate supplementation. Maintaining a firm stance against premature settlements protects your long-term financial security and ensures your property is restored to its pre-loss condition.
What Are the Most Common Pitfalls During a Property Claim?
Navigating an insurance claim without professional guidance exposes property owners to numerous procedural traps that can permanently diminish final settlement payouts. One major pitfall is failing to read policy endorsements and exclusions carefully, leading to missed deadlines for submitting sworn proofs of loss. Another common error is discarding damaged items before the insurance adjuster has a chance to inspect and catalog them, which invalidates content claims. Furthermore, relying entirely on contractor estimates that lack insurance formatting often leads to bitter disputes with carrier adjusters over pricing methodologies. Avoiding these missteps requires proactive organization, strict adherence to policy guidelines, and expert collaboration from seasoned claims professionals.
How Can Comprehensive Support Streamline Your Recovery Process?
Rebuilding after a devastating fire requires coordinating dozens of moving parts, from temporary housing logistics to specialized environmental remediation and structural reconstruction. Property owners who attempt to manage these responsibilities while maintaining full-time careers or running businesses often experience severe burnout and administrative fatigue. Partnering with a dedicated firm simplifies every logistical hurdle by establishing a single, authoritative point of contact for all communication with your insurance carrier. To explore specialized guidance tailored to devastating fire losses, you can review our fire damage services to understand how we manage complex claims from inception to payout. This comprehensive oversight eliminates guesswork, accelerates settlement timelines, and ensures that no eligible coverage provision is left unclaimed.
When Is the Right Time to Contact Our Professional Team?
Timing is everything when protecting your rights as a policyholder facing a major property loss in the Bay State. Reaching out for professional guidance early ensures that critical evidence is preserved, paperwork is filed accurately, and your insurance carrier treats your claim with the seriousness it deserves. You can discover more about our regional coverage and client services by visiting the home page to learn how we assist homeowners and business owners navigate challenging property insurance disputes. Whether you are dealing with active smoke contamination, structural damage, or a stalled insurance claim, expert help is available to guide your recovery. Taking action today provides the clarity and confidence required to rebuild your property and restore your peace of mind.
Frequently Asked Questions
What does a fire damage claim adjuster Massachusetts do for policyholders?
A professional adjuster evaluates the full extent of structural and personal property damage, reviews your insurance policy to identify applicable coverages, prepares a detailed line-item repair estimate, and negotiates directly with the insurance company to secure an equitable financial settlement.
When should I hire an independent claims adjuster after a fire?
You should hire an independent adjuster as soon as possible after the fire is extinguished and safety is secured, ideally before you give any recorded statements or accept preliminary settlement checks from your insurance carrier.
Do insurance companies charge upfront fees for public adjusting services?
Reputable public adjusting firms do not charge upfront consultation fees; instead, they operate on a contingency fee basis, meaning they only collect an agreed-upon percentage after you receive your financial settlement from the insurer.
Can an independent adjuster help if my insurance claim was already underpaid?
Yes, experienced adjusters can reopen closed or underpaid claims by conducting thorough reinspections, uncovering missed structural and smoke damages, and submitting supplemental documentation to challenge the initial low payout.
How do I initiate a consultation with Marinilli Associates?
You can easily start your recovery process by connecting with our expert team through our contact us portal to schedule a free, no-obligation review of your property damage claim.
Conclusion
Recovering from a catastrophic fire requires immense emotional resilience, physical endurance, and meticulous administrative effort to secure the financial recovery you deserve. Attempting to battle corporate insurance adjusters alone often leaves property owners underfunded and overwhelmed during their greatest hour of need. By partnering with Marinilli Associates, you gain a dedicated advocate whose sole mission is to protect your rights, maximize your policy entitlements, and expedite your property restoration. From conducting exhaustive damage audits to negotiating aggressive settlement terms, experienced professionals ensure that your insurance policy works entirely for you. Take control of your recovery today by securing trusted expertise and ensuring your property is rebuilt stronger than ever.