How Can a Fire Damage Claim Adjuster in Massachusetts Help Maximize Your Insurance Claim?
October 5, 2026
How Does a Fire Damage Claim Adjuster in Massachusetts Handle Complex Property Claims?
October 13, 2026What Should You Know Before Hiring a Fire Damage Claim Adjuster in Massachusetts?
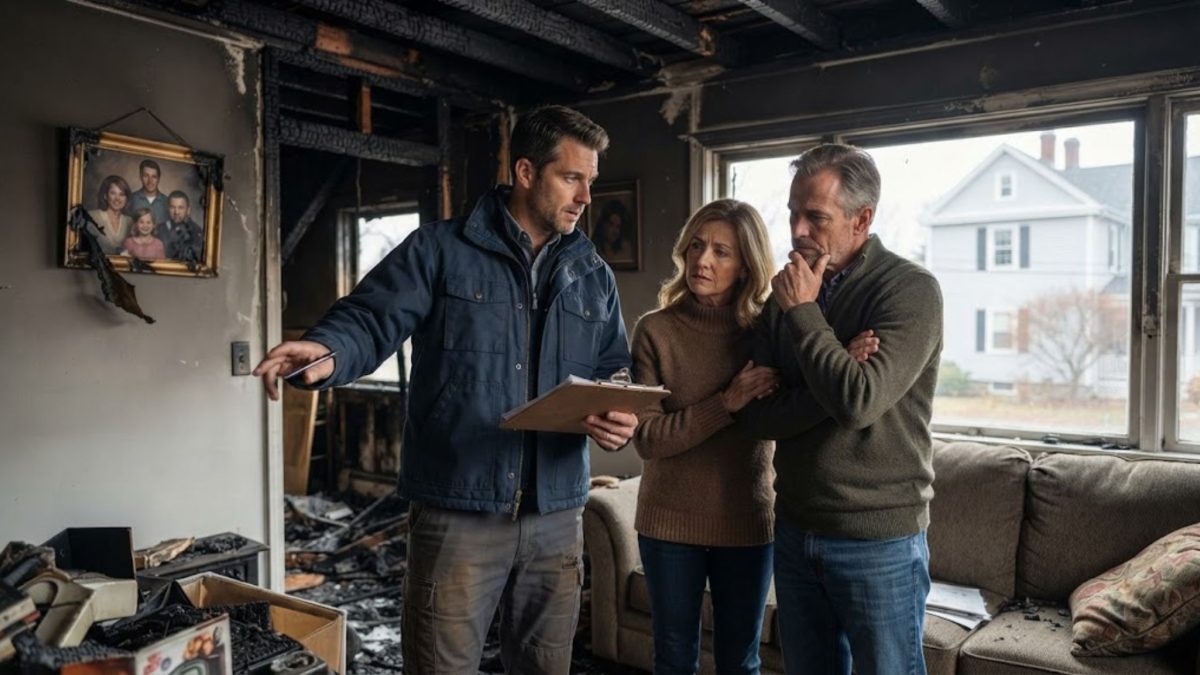
Experiencing a fire in your home or business is one of the most stressful events you can ever face, leaving you to navigate both emotional trauma and complex financial recovery while trying to find a reliable fire damage claim adjuster Massachusetts to protect your rights. When flames tear through your property, the road to rebuilding can feel entirely overwhelming, especially when you realize that your insurance carrier is looking at the loss through a business lens rather than your personal recovery. Homeowners and business owners across New England often feel completely unprepared for the intricate paperwork, exhaustive documentation, and intense negotiations required by modern property insurance policies. Knowing what to look for and understanding how the system works before you sign any agreements can make the difference between a frustrating settlement and a full recovery. By partnering with an experienced professional who understands the local regulations, building codes, and insurance landscape, you can level the playing field and focus your energy on what matters most.
What Does a Fire Damage Claim Adjuster Do During a Property Loss?
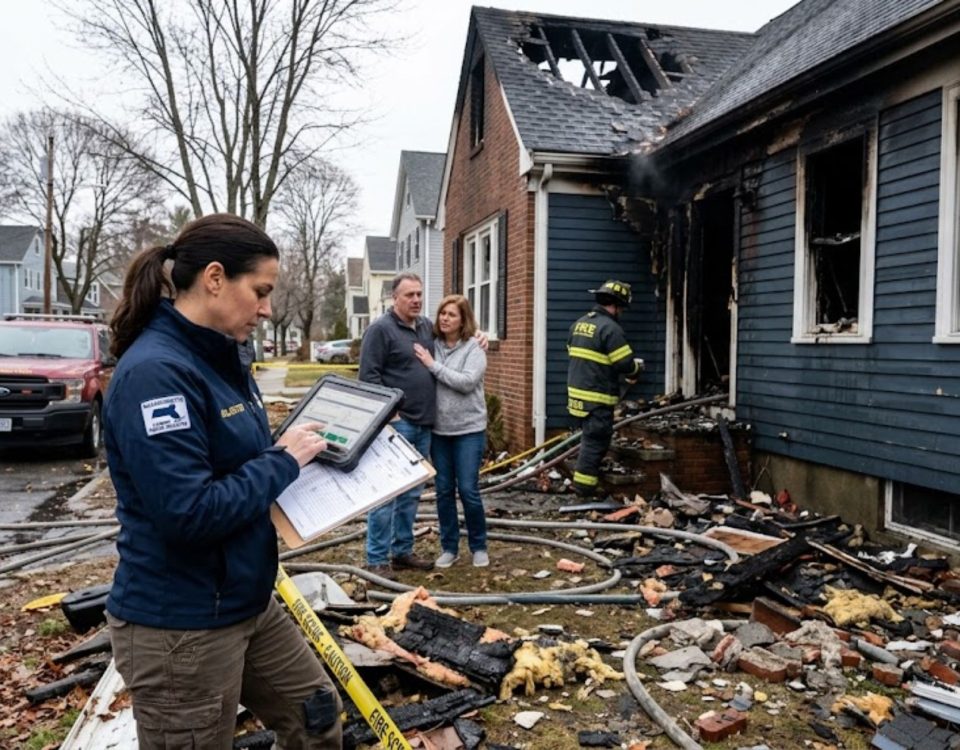
When a devastating fire disrupts your life, hiring a fire damage claim adjuster Massachusetts gives you a dedicated advocate whose sole professional mission is to protect your financial interests against massive insurance corporations. Unlike the insurance company adjuster who represents the carrier paying out the claim, an independent public insurance adjuster works exclusively for you as the policyholder. They examine your insurance policy line by line, identifying every coverage clause, endorsement, and deductible that applies to your specific structural and personal property losses. From conducting meticulous room-by-room inventories of soot-damaged belongings to estimating the exact cost of rebuilding charred framing and drywall, these professionals handle the heavy lifting. They attend every inspection with insurance company representatives, ensuring that hidden damage like smoke permeation inside HVAC systems or water damage from firefighting efforts is never overlooked.
|
Role Comparison |
Insurance Company Adjuster | Public Insurance Adjuster |
| Primary Allegiance | The insurance carrier |
The policyholder |
|
Fee Structure |
Salaried employee of the insurer | Contingency fee based on recovery percentage |
| Focus | Minimizing claim payout and company liability |
Maximizing legitimate policy recovery for the client |
|
Documentation |
Reviews proofs of loss provided by others |
Creates comprehensive, detailed estimates and inventories |
Behind every successful insurance claim is a thorough understanding of policy provisions and local construction pricing that takes years of hands-on experience to master. Many property owners assume that their insurance company will automatically calculate and pay out the maximum possible amount for their losses without extensive proof. In reality, insurance carriers expect detailed line-item documentation for every single damaged item, piece of furniture, and structural component affected by the blaze. A qualified professional compiles these figures using industry-standard estimating software that matches local labor and material costs across the Commonwealth. This level of precision prevents lowball initial offers and ensures that your final payout reflects true replacement costs rather than depreciated value.
Navigating the aftermath of a disaster also requires knowing when to seek additional support and how to connect with trusted local experts who can assist with immediate property stabilization and long-term recovery. For example, many property owners find immense value in exploring the comprehensive resources available when learning about Marinilli Associates to understand their background, licensing, and commitment to policyholder advocacy. Knowing the history and operational standards of the firm handling your case builds confidence during a time when uncertainty is high and financial decisions carry lifelong consequences. Transparency, clear communication, and a proven track record of handling complex residential and commercial losses are vital indicators of a trustworthy partner.
How Does the Insurance Claim Process Work After a Fire?
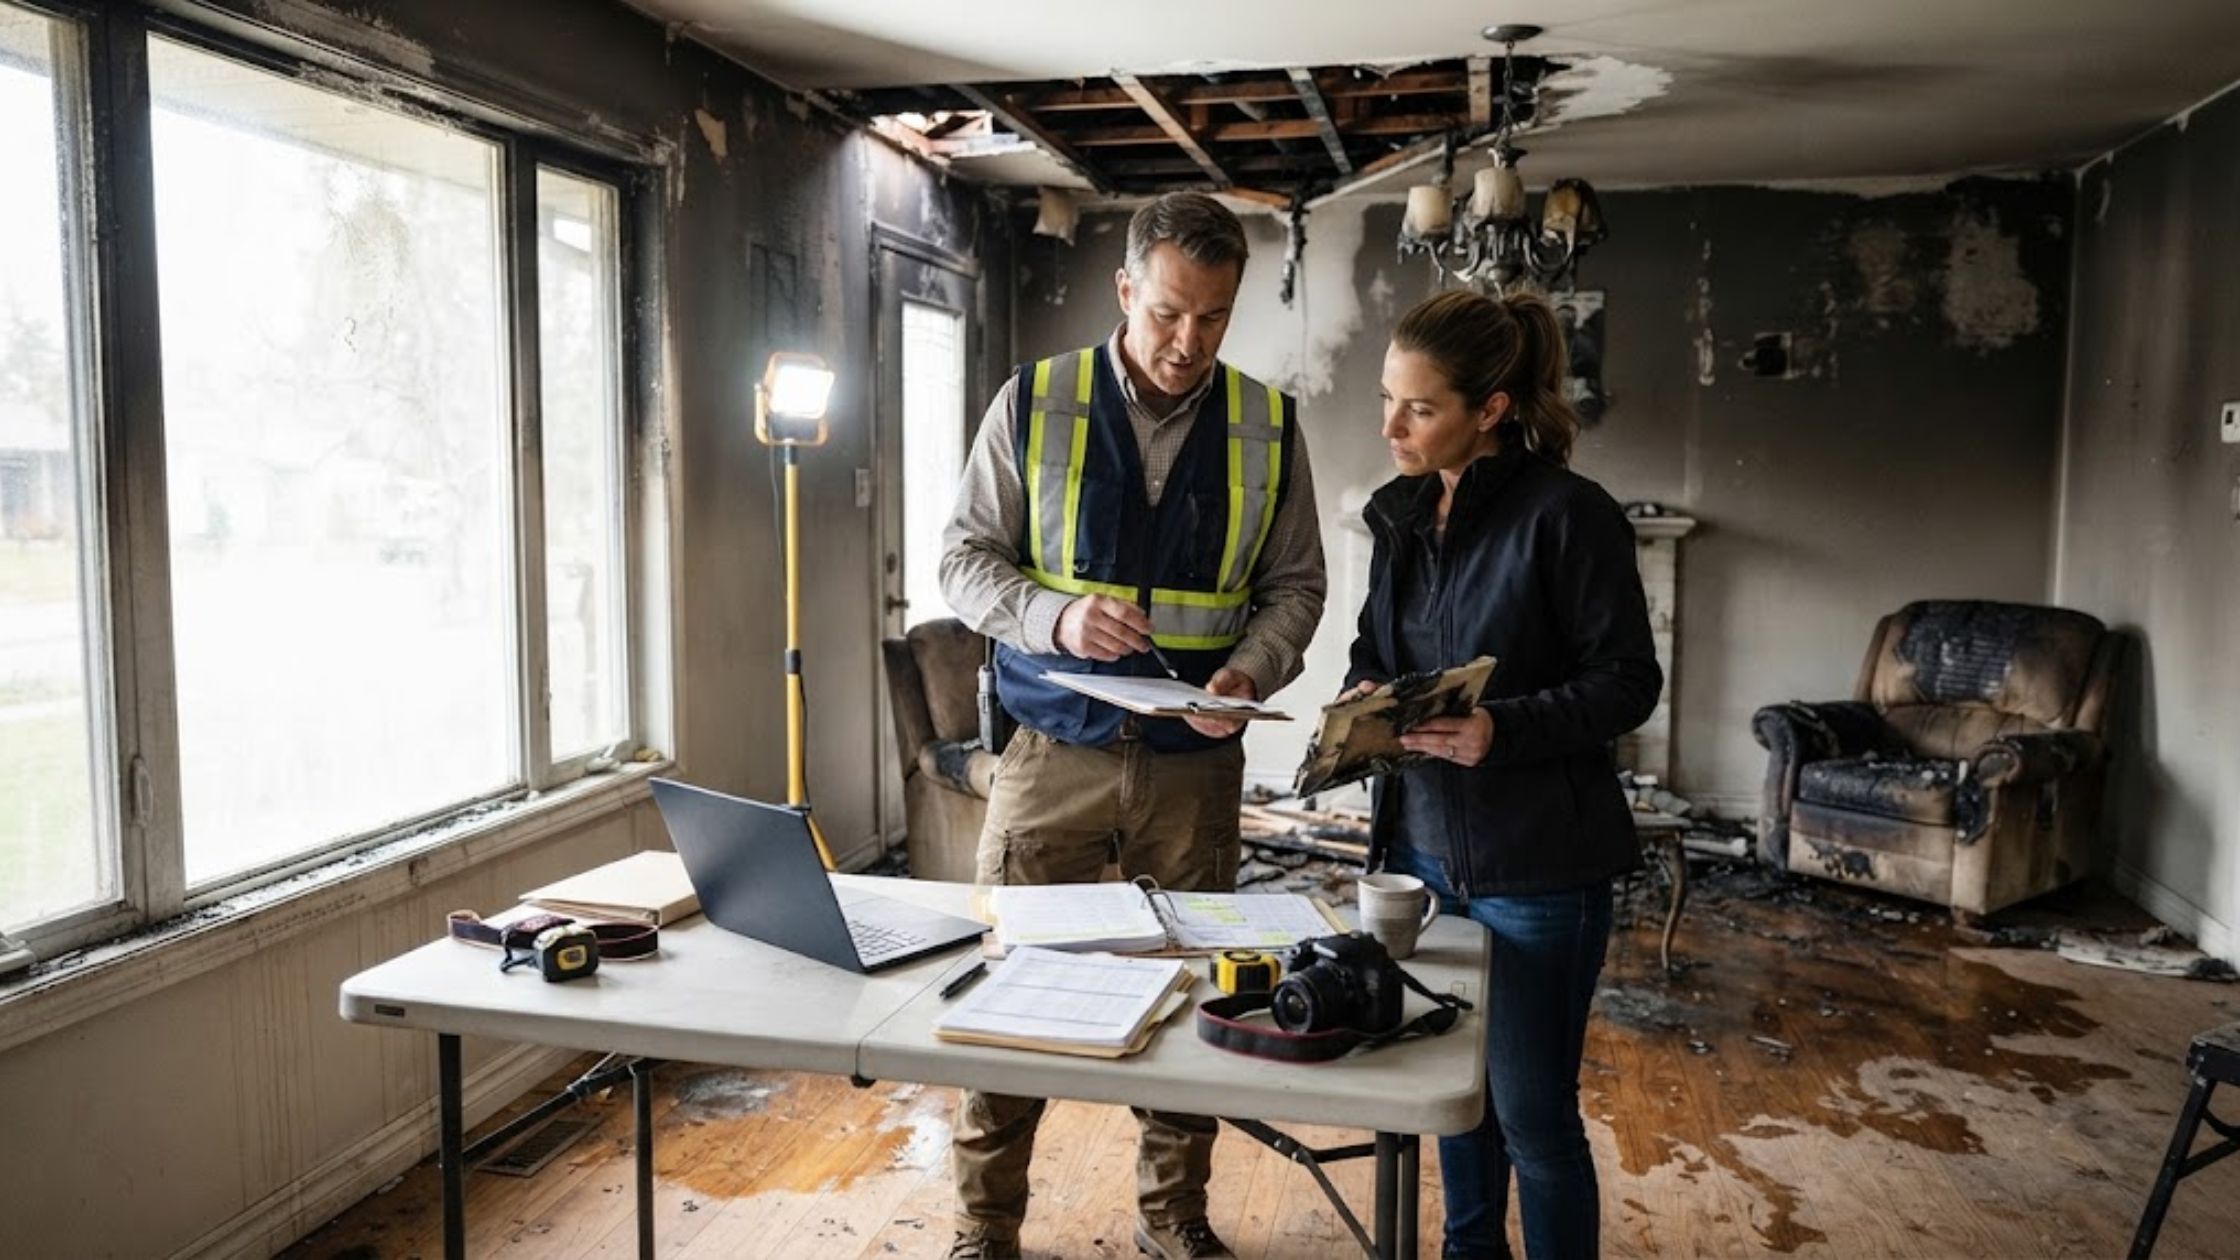
The insurance claim process begins the moment you report the loss to your carrier, triggering a sequence of events that requires careful documentation and strict adherence to policy conditions. Right after the incident, you have a contractual duty to mitigate further damage by boarding up broken windows, securing doors, and preventing weather intrusion where possible. Following this initial emergency response, the insurance company will assign their own adjuster to inspect the property, review the police or fire department report, and assess the overall damage. This is where many policyholders make critical mistakes by speaking casually about the cause of the fire or providing incomplete damage inventories before understanding their full policy entitlements. Having professional representation early in this timeline ensures that all communications are handled properly and that nothing is said or submitted that could jeopardize your payout.
|
Claim Stage |
Typical Actions Required | Potential Pitfalls |
| Initial Reporting | Notify carrier, secure property, mitigate further loss |
Giving premature statements or underestimating damage |
|
Investigation |
Meet adjusters, provide proofs of loss, submit inventories |
Missing hidden soot, smoke, or water damage |
|
Negotiation |
Review carrier estimates, dispute low valuations, settle items |
Accepting initial lowball settlement offers |
|
Rebuilding |
Coordinate repairs, manage depreciation releases, close claim |
Cash flow issues due to delayed advance payments |
As the claim progresses, you will need to submit a formal sworn proof of loss, typically within a strict timeframe mandated by your insurance policy language and state regulations. This document must be accompanied by a comprehensive itemized inventory of all personal property destroyed, damaged, or contaminated by smoke, complete with age, condition, and replacement costs. Simultaneously, you must work with contractors to develop detailed structural repair estimates that account for current building codes, zoning updates, and specialized remediation techniques. Managing these parallel tracks while dealing with temporary displacement can easily become a full-time job that overwhelms even the most organized property owners. Delegating these responsibilities to a skilled specialist allows you to maintain your normal routine or focus on your family and business operations.
When it comes to securing specialized guidance for residential or commercial property losses, exploring dedicated resources such as Marinilli Associates fire damage services can provide invaluable clarity on how to structure your claim documentation. These specialized services focus on identifying every covered peril, from direct flame destruction to corrosive soot residue and hidden structural water damage. Ensuring that every facet of the loss is fully captured in your claim submission prevents out-of-pocket expenses later in the rebuilding process when unexpected construction costs arise.
What Are the Benefits of Hiring a Public Adjuster Over Handling It Yourself?
Handling a major property loss independently often puts policyholders at a severe disadvantage because insurance company adjusters handle hundreds of claims every year while most property owners experience only one or two in a lifetime. Insurance policies are dense legal contracts written by corporate legal teams, filled with complex exclusions, co-insurance clauses, and conditions that can easily trip up an untrained individual. A licensed public adjuster brings deep technical knowledge of these contracts, ensuring that ambiguous wording is interpreted in your favor rather than the insurance company’s bottom line. They know how to identify hidden coverage extensions within your policy, such as ordinance or law coverage, debris removal allowances, and additional living expense provisions. This expertise frequently uncovers thousands of dollars in legitimate entitlements that policy owners would otherwise leave on the table.
Beyond policy interpretation, professional advocacy significantly reduces the administrative burden and emotional fatigue associated with chronic back-and-forth communication with insurance representatives. Instead of spending your evenings arguing over line-item depreciation percentages or waiting on hold for claim status updates, you have a dedicated professional managing the workflow. This structural support is why many families and business owners turn to established professionals like Marinilli Associates when they need a reliable partner to shoulder the burden of complex insurance negotiations. The peace of mind that comes from knowing your financial recovery is being managed by seasoned experts allows you to focus entirely on personal healing and business continuity.
Another major advantage of working with a licensed professional is their proficiency in utilizing advanced estimating tools and building science knowledge to counter low insurance settlement offers. Insurance company estimates often rely on regional pricing databases that may not reflect current local labor shortages or material cost fluctuations in your specific municipality. Your advocate cross-references these figures with actual contractor bids and comprehensive scopes of work, presenting undeniable evidence to support higher payout demands. Furthermore, because these professionals operate on a contingency fee basis where they only get paid a percentage after you successfully collect from the insurer, their financial incentives are completely aligned with yours. You face zero upfront costs or financial risks, making expert representation accessible when you need it most.
If you are ready to discuss your specific situation with an experienced team, visiting the Marinilli Associates homepage provides an easy entry point to review their credentials, service areas, and client testimonials. Seeing how other property owners in New England have successfully navigated devastating losses can offer reassurance and practical insight into what your own recovery process will entail. Taking that first step toward professional representation transforms a lonely, frustrating battle into a structured, strategic campaign for fair compensation.
How Do You Choose the Right Public Adjuster for Your Needs?
Selecting the right professional to represent your fire damage claim requires careful vetting of licensing credentials, industry experience, and professional reputation within your local community. In the Commonwealth, public insurance adjusters must be officially licensed by the Division of Insurance, ensuring they have met rigorous educational and ethical standards set by regulatory authorities. Always verify that any adjuster you consider hiring holds an active license and can provide proof of bonding and professional liability insurance. Additionally, look for professionals who possess deep local knowledge of regional building practices, municipal inspection requirements, and common architectural styles found throughout New England. A firm with decades of regional experience will instantly recognize the unique structural challenges posed by older New England homes and commercial buildings.
When evaluating potential candidates, ask detailed questions about their past experience with fires of a similar scale, as well as their familiarity with your specific insurance carrier’s claims handling tendencies. A reputable professional will gladly provide references from past clients, explain their fee structure with absolute transparency, and outline their communication cadence throughout the life of the claim. To initiate this conversation without any financial obligation, you can easily reach out to Marinilli Associates to schedule a free incident review and discuss the specifics of your property loss. Direct communication during your initial consultation helps you gauge their responsiveness, empathy, and professional competence before signing any representation agreements.
Avoiding predatory actors is another crucial aspect of choosing the right representative, as unscrupulous operators sometimes target distressed property owners immediately following a major disaster. Legitimate public adjusters adhere to strict ethical codes, carry proper state credentials, and never employ high-pressure sales tactics or demand upfront retainers before evaluating your loss. Take your time to review contracts carefully, ensuring you understand the exact contingency percentage, cancellation terms, and scope of services provided. A trustworthy firm will encourage you to read every word of the agreement and answer all your questions with patience and clarity.
Frequently Asked Questions About Fire Insurance Claims
When should I hire a fire damage claim adjuster massachusetts?
The best time to hire a public adjuster is as soon as possible after the fire has been extinguished and the property is safe to enter. Bringing an expert in early ensures that emergency mitigation is handled correctly, no initial evidence is lost, and all communications with the insurance carrier are properly managed from day one.
How much do public insurance adjusters charge for their services?
Public adjusters typically work on a contingency fee basis, meaning they charge a predetermined percentage of the final insurance claim recovery payout. There are no upfront fees or out-of-pocket costs, and the fee is only collected after the insurance company pays out your settlement funds.
Will hiring an independent adjuster cancel my insurance policy?
No, hiring a licensed public adjuster to represent your interests is your legal right as a policyholder under state insurance regulations. Insurance companies cannot cancel, non-renew, or penalize your policy simply because you chose to exercise your right to professional representation.
Can a public adjuster help if my insurance claim was already denied?
Yes, experienced public adjusters frequently review previously denied or underpaid claims to uncover overlooked policy provisions, gather additional technical documentation, and reopen negotiations with the insurance carrier. Their expertise often successfully overturns initial denials or significantly increases inadequate payouts.
What types of property damage do public adjusters handle?
While fire and smoke losses are among the most common engagements, licensed public adjusters also handle water damage, windstorms, hurricanes, structural collapses, and related perils. They provide comprehensive loss assessment and negotiation services for both residential homeowners and commercial property owners across the region.
Conclusion
Navigating the aftermath of a devastating property fire requires resilience, strategic planning, and the right professional guidance to ensure you receive the financial settlement you rightfully deserve. Trying to manage complex insurance policies, detailed inventories, and aggressive carrier negotiations on your own can easily lead to severe undervaluation and unnecessary financial stress. By understanding how the claims process works, recognizing the value of independent advocacy, and partnering with trusted experts like Marinilli Associates, you can protect your investment and rebuild with confidence. Taking action today to secure a qualified fire damage claim adjuster massachusetts puts your recovery back on track and ensures that your voice is powerfully represented against corporate insurance interests.