How Much Does a Fire Damage Claims Adjuster Cost, and Is It Worth It?
September 25, 2026
What Should You Know Before Hiring a Fire Damage Claim Adjuster in Massachusetts?
October 7, 2026How Can a Fire Damage Claim Adjuster in Massachusetts Help Maximize Your Insurance Claim?
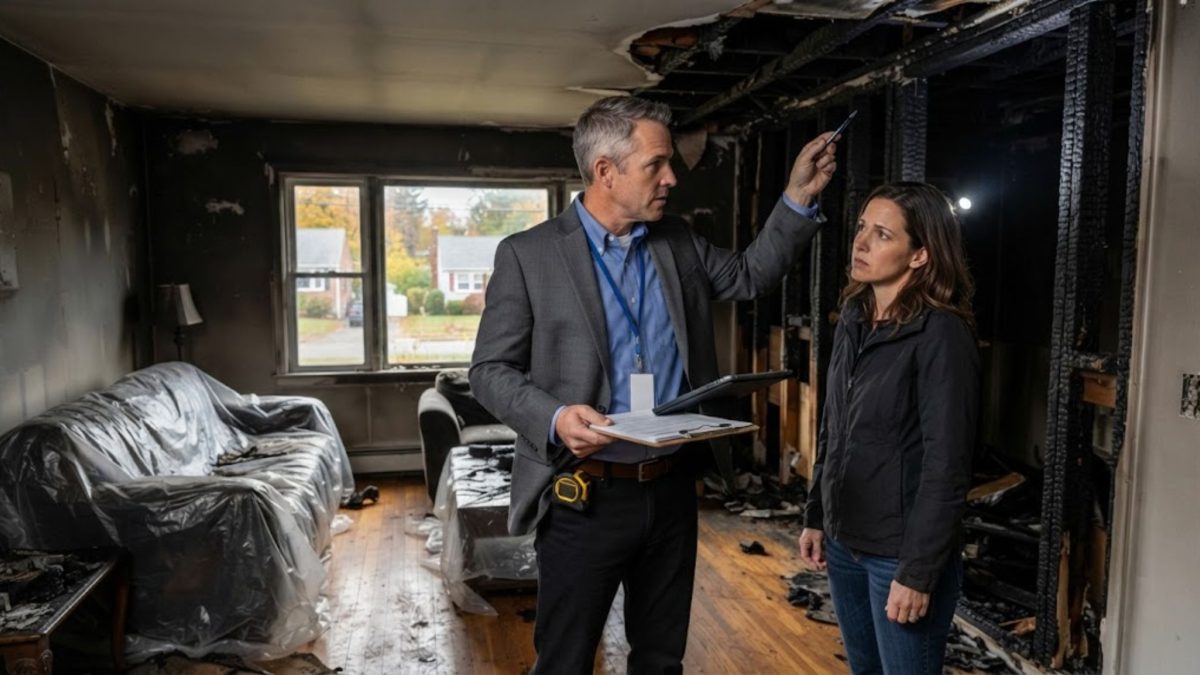
Experiencing a fire in your home or business is one of the most stressful events you can ever face, leaving you to deal with emotional trauma while wondering how you will ever recover your losses and navigate the complex maze of your insurance policy, which is precisely why hiring a fire damage claim adjuster massachusetts can make the absolute difference between walking away with a fraction of what you deserve or securing the full financial recovery needed to rebuild your life. When the smoke clears and the shock begins to wear off, the reality of filing an insurance claim sets in, bringing with it an overwhelming mountain of paperwork, detailed inventories, and tense negotiations with insurance company representatives whose primary goal is to minimize payouts. Navigating this arduous process alone often puts policyholders at a severe disadvantage because insurance carriers employ seasoned professionals and adjusters whose daily job is to protect corporate bottom lines rather than your best interests. By bringing an independent advocate into your corner, you level the playing field immediately, ensuring that every single square foot of structural damage, every piece of soot-stained furniture, and every hidden consequence of smoke and water is thoroughly accounted for, valued accurately, and presented to your insurer with professional precision.
What Does a Fire Damage Claim Adjuster Do After a Property Loss?
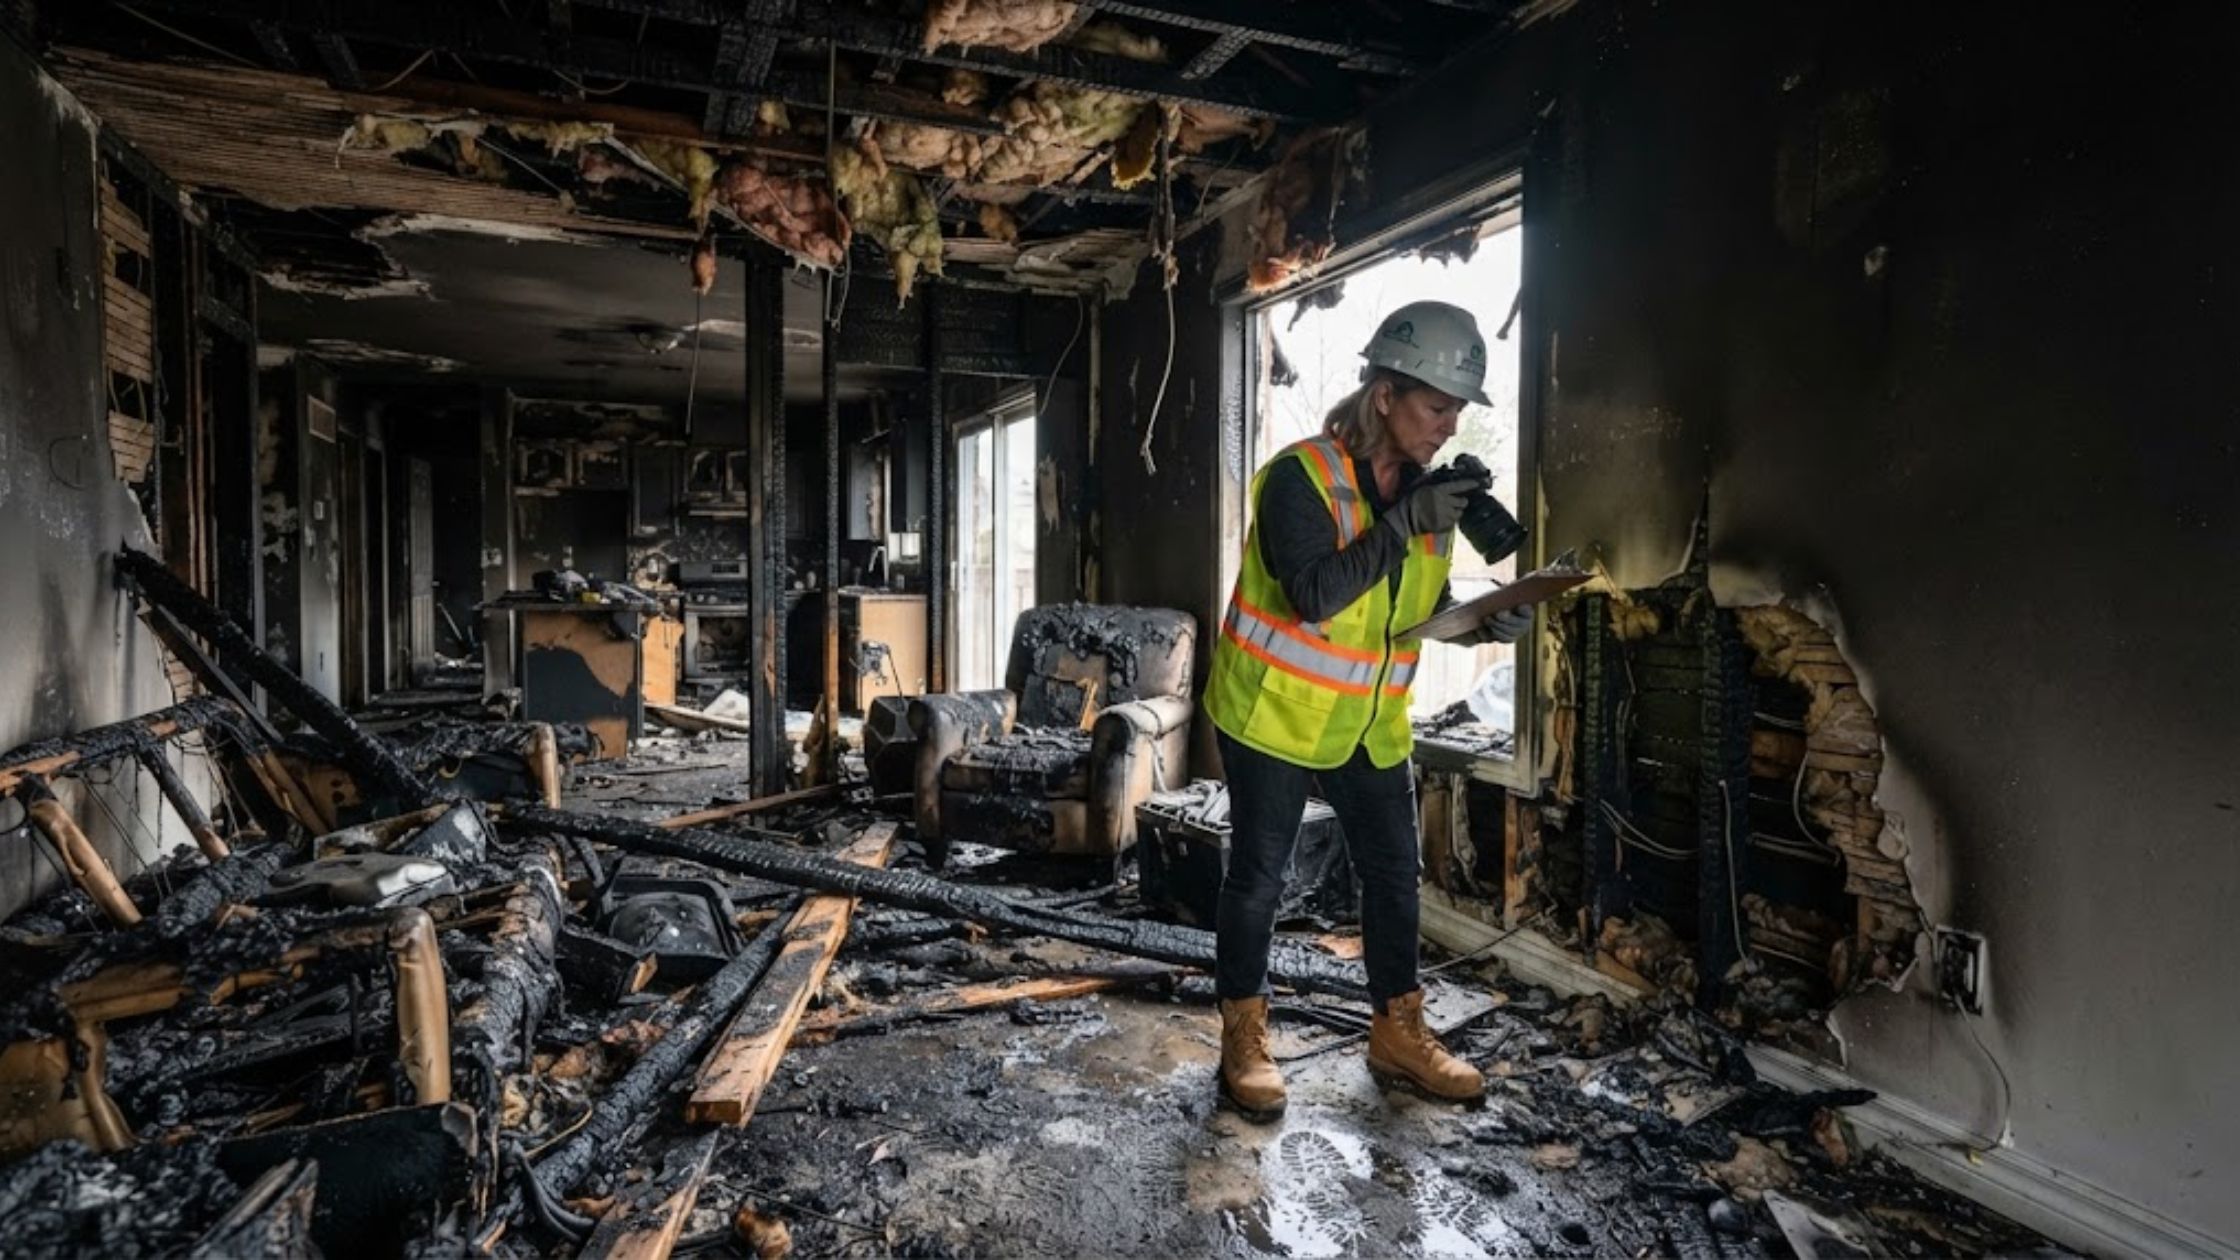
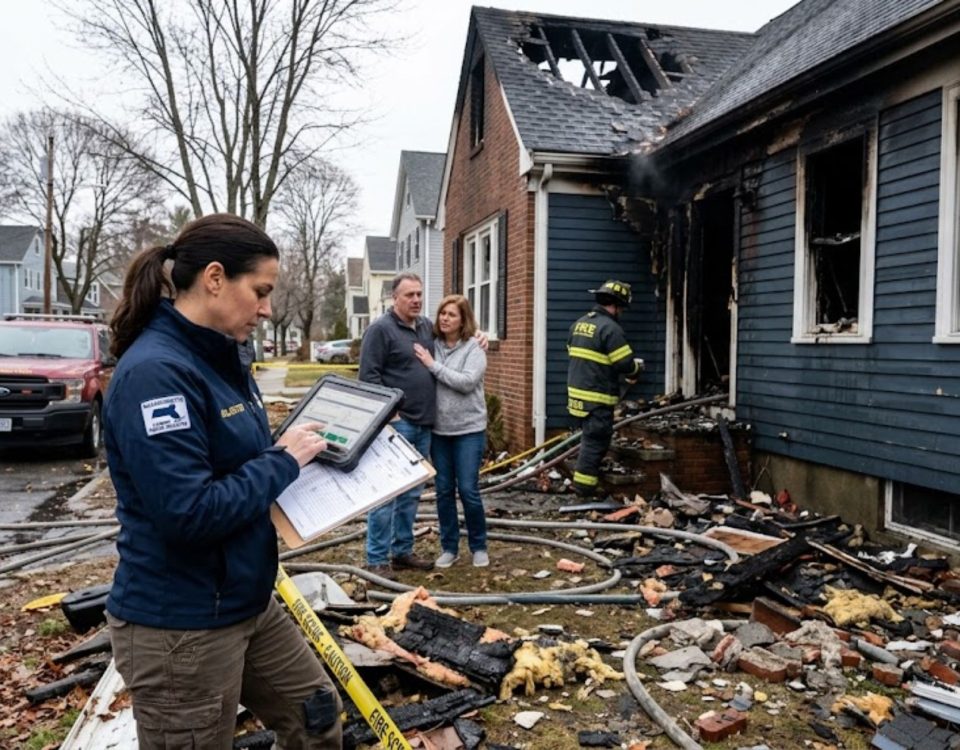
When you partner with a fire damage claim adjuster Massachusetts, you gain an experienced professional who takes over the heavy lifting of your property loss claim from day one, allowing you to focus entirely on your family, your business, and your personal recovery. The role of a dedicated public adjuster extends far beyond simply filling out forms; it involves a comprehensive investigation of your insurance policy to uncover every coverage limit, endorsement, and provision that can be leveraged to maximize your payout. They begin by conducting an independent, meticulous inspection of the property, documenting every tier of destruction from obvious structural charring to insidious smoke infiltration that has traveled deep into the HVAC system and wall cavities. This exhaustive approach ensures that nothing is overlooked, which is a common pitfall for exhausted property owners who try to inventory charred belongings and structural repairs while dealing with temporary displacement. Furthermore, your adjuster acts as the sole point of contact for the insurance company, handling every phone call, email, and on-site meeting so that you do not accidentally say something that could jeopardize the full valuation of your claim.
To understand how an independent professional transforms the recovery trajectory, it helps to examine the core responsibilities they shoulder throughout the lifecycle of a property insurance claim.
|
Phase of Claim |
Insurance Company Adjuster Role | Independent Public Adjuster Role |
| Initial Inspection | Evaluates damage with a focus on minimizing payout and finding policy exclusions. |
Conducts a comprehensive, independent assessment to capture every hidden loss. |
|
Documentation |
Relies on minimal baseline estimates and quick visual checks of the property. |
Builds line-by-line Xactimate estimates, detailed room-by-room inventories, and engineer reports. |
|
Negotiation |
Pushes back on repair costs and delays approvals using technical insurance jargon. |
Advocates aggressively for your maximum entitlement, citing policy clauses and local building codes. |
Conducting Comprehensive Property Inspections
An initial inspection following a disaster requires a sharp, trained eye that knows precisely where structural integrity has been compromised and where hidden perils like toxic soot and water saturation lurk. Independent professionals step in immediately to secure the property, coordinate emergency board-ups, and prevent further deterioration caused by weather or vandalism before it can compound your existing losses. They use specialized moisture meters, thermal imaging cameras, and air quality assessments to uncover damage that standard visual inspections entirely miss, creating an unassailable foundation for your financial recovery. This level of granular detail guarantees that when the formal proof of loss is submitted, it reflects the true, uncompromised cost of restoring your property back to its pre-loss condition rather than a superficial patch-up job.
Establishing Exact Repair and Replacement Costs
Calculating the true cost of rebuilding a fire-damaged structure is a complex science that involves current material pricing, local labor rates, and mandatory building code updates that are often triggered during major renovations. Insurance carriers frequently rely on generalized software or depreciated pricing models that do not reflect current market realities, leaving policyholders short when contractors actually begin work. Your representative compiles detailed, line-by-line estimates using the exact same software platforms that insurance companies trust, ensuring that every framing member, drywall sheet, electrical run, and custom finish is priced accurately. For personal property, they guide you through the tedious task of cataloging ruined possessions, researching replacement costs, and factoring in inflation and local taxes so you are not shortchanged on your contents coverage.
Why Should You Hire a Public Adjuster Instead of Relying on Your Insurance Company’s Adjuster?
Many homeowners and business owners mistakenly believe that the adjuster sent by their insurance company is an unbiased referee whose job is to ensure they get a fair settlement, but the reality is that company adjusters are employees or contracted agents of the insurer with a fiduciary duty to protect the carrier’s financial interests. When you rely solely on the insurance company’s assessment, you are relying on an evaluation designed to control costs, which often results in undervalued claims, delayed approvals, and omitted coverage categories. Marinilli Associates operates entirely on the other side of that equation, representing policyholders exclusively and bringing over thirty years of advocacy, technical estimating capability, and deep knowledge of policy language to every single engagement. Our team includes six licensed public adjusters with more than 100 years of combined experience, giving you the collective weight of seasoned experts who know how to interpret ambiguous policy wording and stand up to heavy-handed insurance tactics. You can learn more about our foundational commitment to client advocacy by visiting About Marinilli Associates, where we outline our history of standing shoulder-to-shoulder with property owners across New England.
Working with an independent firm changes the entire dynamic of the claims process because your advocate’s success is directly tied to the outcome of your settlement, aligning their incentives completely with your goal of maximum recovery. Insurance policies are dense legal contracts filled with intricate conditions, deadlines, and technical terminology that can trip up even the most diligent policyholder, leading to accidental claim denials or reduced payouts. Your public adjuster decodes these contracts, ensures that all formal notices and proofs of loss are submitted well within statutory deadlines, and prevents the insurer from using procedural technicalities to reduce your payout. By shifting the burden of proof onto experienced professionals who speak the insurance industry’s language fluently, you remove the stress of combatting corporate bureaucracy while securing a comprehensive financial settlement.
|
Traditional Insurance Adjuster Approach |
Independent Public Adjuster Approach |
| Works for and answers to the insurance carrier. |
Works exclusively for you, the policyholder. |
|
Minimizes payout to protect corporate profits. |
Maximizes recovery to ensure complete property restoration. |
| Relies on baseline or depreciated repair estimates. |
Utilizes current market pricing and building code requirements. |
|
Place the administrative burden of proof entirely on you. |
Manages all documentation, inventories, and negotiations. |
How Does Smoke and Soot Damage Complicate Fire Insurance Claims?
While the flames themselves cause obvious catastrophic destruction, the invisible and pervasive aftermath of smoke, soot, and toxic chemical residue often presents the greatest challenge during the restoration and insurance settlement process. Soot is acidic, corrosive, and incredibly stubborn, meaning that if it is not professionally cleaned and treated within days of the fire, it can permanently etch glass, corrode metal fixtures, ruin electronics, and destroy textiles throughout your entire property. Insurance carriers frequently attempt to settle smoke damage claims by authorizing quick surface wipe-downs and painting over affected drywall, a superficial fix that leaves lingering odors and hidden chemical residues trapped within the structure. A professional adjuster ensures that specialized remediation protocols, such as thermal fogging, ozone treatment, and complete ductwork decontamination, are fully accounted for in the initial claim estimate so your living environment is truly safe and restored. For specialized guidance on handling these intricate losses, you can explore our dedicated services at Fire Damage Public Adjuster, detailing how we handle complex soot and structural complications.
Furthermore, the odor of smoke permeates porous building materials, furniture insulation, and personal belongings, requiring extensive testing and professional restoration techniques that standard cleaning services cannot provide. If smoke mitigation is handled improperly, toxic residues can off-gas for months after you move back in, causing ongoing health issues and continuous property degradation that your insurance policy should have covered from the start. Your adjuster works with certified industrial hygienists and environmental specialists to test air quality, document chemical contamination levels, and prove to the insurance company that intensive remediation is an absolute necessity. This scientific, evidence-based approach prevents insurers from dismissing smoke damage as a minor cosmetic issue and secures the funding required for thorough, professional-grade cleaning and replacement.
What Steps Should You Take Immediately After a Fire Occurs?
The moments immediately following a fire are chaotic and emotionally draining, yet the actions you take during this critical window can significantly impact the ultimate success and valuation of your insurance claim. Your first priority must always be the safety and physical well-being of your family and pets, ensuring everyone is evacuated and accounted for before emergency responders arrive to secure the scene. Once the fire department has extinguished the blaze and cleared the property as safe to re-enter, you need to begin documenting the initial state of the disaster as thoroughly as possible while avoiding actions that could compromise your insurance coverage. To get immediate professional advice and start your recovery on the right footing, you can visit Marinilli Associates to schedule a free incident review and access around-the-clock emergency response support.
Taking a methodical approach to the immediate aftermath protects your rights under your insurance contract and lays the groundwork for a smooth, well-documented claim filing. Below are the essential steps you should take right after securing emergency safety:
- Contact Emergency Services: Ensure the fire department has fully extinguished the blaze and obtain a copy of the official incident report for your records.
- Secure the Property: Arrange for emergency board-up services to prevent weather intrusion, theft, or unauthorized entry into your damaged home or business.
- Notify Your Insurance Carrier: Report the loss to your insurance company promptly to initiate the claim, but avoid giving detailed recorded statements until you have professional representation.
- Document Everything: Take clear, high-resolution photographs and videos of every damaged room, structural element, and personal possession before any cleanup begins.
- Mitigate Further Loss: Take reasonable, cost-effective steps to prevent additional damage, such as shutting off compromised utilities or covering broken windows, and keep all associated receipts.
How Do Insurance Policies Handle Additional Living Expenses and Business Interruption?
When a fire renders your home uninhabitable or forces your business to shut its doors, the financial burden extends far beyond physical repair costs, touching every aspect of your daily life and ongoing operational expenses. Most standard homeowner and commercial property insurance policies include coverage for Additional Living Expenses or Business Interruption, designed to reimburse you for the extra costs of maintaining your standard of living or keeping your business afloat during repairs. However, insurance companies often scrutinize these claims heavily, challenging every hotel bill, temporary rental payment, and lost revenue calculation to minimize their financial payout during your time of crisis. A knowledgeable public adjuster audits your policy to identify every applicable living expense provision, tracking your out-of-pocket costs meticulously and presenting them with the exact documentation insurers require for prompt reimbursement.
For displaced families, this coverage ensures you can rent a comparable home, maintain reasonable meal allowances, and keep your children in their current schools without suffering financial ruin while your primary residence is being rebuilt from the studs. For business owners, interrupted cash flow can spell permanent closure if overhead, payroll, and lost profits are not accurately calculated and recovered through your business interruption endorsement. Your adjuster collaborates with forensic accountants to review your financial records, profit margins, and fixed expenses, building an undeniable case that proves your true financial losses to the insurance carrier. If you are facing complex residential or commercial displacement and need immediate assistance, you can reach out directly through Contact Us to speak with an experienced professional about your specific situation.
Frequently Asked Questions About Fire Damage Insurance Claims
What is a fire damage claim adjuster in Massachusetts?
A fire damage claim adjuster is a licensed professional who represents policyholders, not insurance companies, to evaluate, document, and negotiate property damage claims. They ensure that all structural damage, smoke remediation, and personal property losses are fully accounted for to secure a maximum financial settlement.
Why should I hire an independent public adjuster instead of using the insurance company adjuster?
The insurance company adjuster works for the carrier and has a financial incentive to minimize your payout. An independent public adjuster works exclusively for you, utilizing technical expertise and market data to advocate for your best interests throughout the claims process.
How are public adjusters compensated for their services?
Reputable public adjusters operate on a contingency fee basis, meaning they take a small, agreed-upon percentage of the final insurance recovery only after you have been paid. There are typically no upfront consultation charges or out-of-pocket fees to get started.
Can a public adjuster help if my insurance claim was already denied or underpaid?
Yes, public adjusters frequently step in to review previously denied or severely underpaid claims. They can reopen the claim, conduct a more thorough re-inspection, and submit supplemental documentation to challenge the insurance company’s initial decision.
How soon after a fire should I contact a public adjuster?
You should contact a public adjuster as soon as possible after the fire is extinguished and everyone is safe. Early involvement allows them to secure the property, document the initial damage before cleanup alters the scene, and guide all communications with the insurer from day one.
Conclusion
Navigating the aftermath of a property fire is an immense challenge, but you do not have to face the complexities of your insurance company alone when professional advocacy is within reach. By partnering with an experienced fire damage claim adjuster Massachusetts, you ensure that your rights are protected, your losses are fully documented, and your settlement reflects the true cost of rebuilding your property and your peace of mind. Marinilli Associates stands ready to bring over three decades of dedicated New England experience, rigorous estimating capabilities, and unwavering policyholder advocacy to your corner from the very first notice of loss to the final settlement check. Do not let insurance company tactics diminish your rightful recovery when expert guidance can maximize your claim and pave the way for a complete, stress-free fresh start.