How Can a Fire Damage Claims Adjuster Help Maximize Your Insurance Settlement?
September 22, 2026
How Much Does a Fire Damage Claims Adjuster Cost, and Is It Worth It?
September 25, 2026When Should You Hire a Fire Damage Claims Adjuster After a House Fire?
Experiencing a residential fire is one of the most emotionally devastating events a homeowner can face, leaving behind not just physical destruction, but a complex maze of recovery tasks. In the immediate aftermath, when your focus should entirely be on family safety and emotional healing, you are suddenly expected to navigate a complicated insurance maze with a fire damage claims adjuster. This is precisely why partnering with an experienced advocate can completely change your recovery trajectory, turning a stressful ordeal into a structured path toward fair compensation. Insurance policies are notoriously dense documents filled with complex terminology, exclusions, and valuation methods that favor the carrier rather than the policyholder. Bringing in professional advocacy early ensures your rights are protected from day one while you focus on rebuilding your life and finding temporary housing. To explore more about how we support homeowners through property crises, you can visit Marinilli Associates right now.
Should You Hire a Public Adjuster After a Fire?
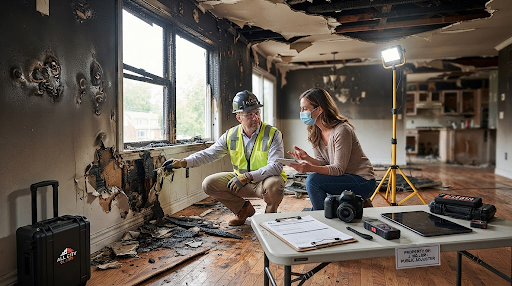
When should you hire a fire damage claims adjuster to handle your losses? The short answer is as soon as humanly possible after the emergency responders clear the scene and it is safe to assess the property. Many homeowners make the mistake of waiting until their insurance company’s adjuster has already inspected the home and made an initial settlement offer. By that time, crucial details regarding soot migration, smoke infiltration, and structural compromise may have been overlooked or minimized. Bringing an expert on board early allows for a thorough, independent assessment of every square foot of your property. This proactive timeline guarantees that no hidden damage gets swept under the rug or left out of the initial loss report submitted to your insurance provider.
Insurance companies employ professional adjusters whose primary financial incentive is to minimize payouts and protect the carrier’s bottom line. When you attempt to manage residential fire insurance claims alone, you are playing a high-stakes game without a playbook against seasoned negotiators. A dedicated public advocate levels the playing field by conducting an exhaustive, independent evaluation of your home structure, personal belongings, and temporary living expenses. They meticulously document every single loss, from structural beams compromised by intense heat to microscopic soot particles embedded in your HVAC system. Without this level of granular detail, most homeowners inadvertently settle for a fraction of what their policy actually entitles them to receive.
Navigating the aftermath of a disaster requires deep knowledge of building codes, policy endorsements, and local construction pricing. If you are wondering whether to hire a public adjuster after fire incidents, consider the sheer volume of paperwork, inventory lists, and contractor estimates required. A professional takes the heavy administrative burden completely off your shoulders, compiling comprehensive proof of loss statements that satisfy strict carrier deadlines. Furthermore, they handle all direct communication with the insurance company, shielding you from aggressive adjusters or confusing requests for documentation. This insulation reduces your stress levels significantly, allowing you to channel your energy where it belongs in your family.
Understanding the True Scope of Fire and Smoke Damage
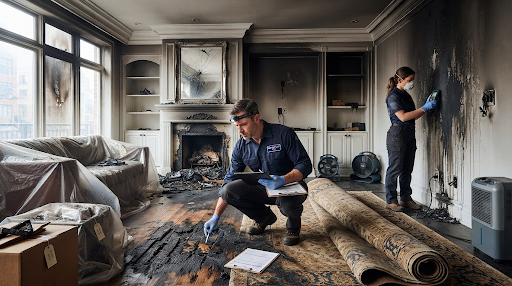
Fire damage extends far beyond the areas touched directly by open flames, encompassing severe structural threats and hidden dangers. Heat can warp steel framing, weaken concrete foundations, and compromise load-bearing walls long after the fire has been extinguished. Smoke and toxic gases travel through HVAC ducts, permeating drywall, insulation, and personal items throughout the entire house. Water used by firefighters also introduces severe secondary issues like mold growth and warping subfloors if not extracted properly. Recognizing these multi-layered complications is essential for securing a payout that covers complete restoration rather than a superficial cosmetic fix.
|
Damage Type |
Primary Cause | Hidden Risk Factors | Restoration Requirement |
| Structural Compromise | Extreme Heat | Weakened framing, warped steel |
Professional engineering assessment |
|
Smoke Infiltration |
Combustion Gases | Toxic residue in HVAC, porous walls | Specialized thermal fogging and sealing |
| Water & Moisture | Firefighting Efforts | Mold proliferation, ruined subfloors |
Industrial dehumidification and extraction |
Evaluating personal property loss is often the most time-consuming and emotionally draining part of any property insurance claim. Insurance companies require an itemized inventory list detailing the age, condition, replacement cost, and actual cash value of every destroyed item. Trying to recall every appliance, piece of clothing, and family heirloom while dealing with trauma is nearly impossible without professional assistance. An experienced advocate helps you methodically catalog every lost possession, ensuring that sentimental and high-value items receive appropriate valuations. They ensure that items you forgot about in the attic or garage are fully accounted for in your final settlement package.
The Financial Benefits of Professional Claim Representation
Many policyholders hesitate to bring in professional representation because they worry about the added cost during an already expensive time. However, reputable firms like Marinilli Associates operate on a contingency fee structure, meaning they only earn a percentage of the settlement after you get paid. Studies consistently show that policyholders who utilize independent representation secure substantially higher payouts than those who navigate the process entirely alone. This net increase in your settlement easily outweighs the adjustment fee while freeing you from costly under-settlement mistakes. Investing in professional advocacy is not an added expense; it is a strategic financial decision that protects your long-term investment.
|
Metric |
Handling Claims Alone | Working With an Adjuster |
|
Average Settlement Payout |
Often significantly lower |
Maximized based on full policy limits |
|
Time Invested by Homeowner |
Hundreds of hours of stressful research |
Minimal administrative burden |
|
Error Risk in Documentation |
High risk of missed items or procedural flaws |
Negligible due to expert oversight |
|
Dispute Resolution |
Stressful, prolonged negotiations |
Efficient, professional advocacy |
Choosing the right partner to guide you through this difficult journey makes all the difference in achieving a successful financial recovery. You can learn more about our commitment to advocacy and client support by visiting about marinilli associates to read our story. Our team understands the nuances of complex residential fire insurance claims and works tirelessly to ensure you receive every dollar you deserve. We take pride in standing shoulder-to-shoulder with homeowners when they need a reliable advocate the most. Let us handle the complexities of your carrier while you focus on creating a safe, stable environment for your loved ones.
Key Timeline Milestones After a House Property Loss
Successfully managing an insurance claim requires strict adherence to notification timelines, proof of loss deadlines, and policy conditions. Missing a single filing deadline or submitting incomplete documentation can give your insurance company grounds to delay, reduce, or deny your claim. A structured timeline ensures every critical phase of the recovery process is executed flawlessly from the initial emergency response to final rebuilding.
- Immediate Response Phase: Ensure family safety, secure emergency housing, and notify your insurance carrier of the loss event.
- Initial Assessment Phase: Engage an independent advocate to document all structural damage, smoke impact, and personal property losses.
- Documentation Phase: Compile comprehensive itemized inventory lists, contractor repair estimates, and proof of loss forms.
- Negotiation Phase: Let your representative challenge lowball offers and negotiate directly with the carrier’s adjusters.
- Settlement and Restoration Phase: Receive the disbursed funds and oversee quality construction to restore your home to its pre-loss condition.
Every phase of this timeline demands meticulous attention to detail and a thorough understanding of policy language and endorsements. For more insights into our specialized approach to property loss management, explore our dedicated service page. We break down the entire lifecycle of a claim so you always know what to expect during each step of the journey. Transparency and open communication form the cornerstone of our client relationships during these challenging times.
How to Prepare for Your Initial Consultation With an Adjuster
Preparing for your first meeting with an independent claim specialist helps streamline the evaluation process and sets clear expectations. Gather your insurance policy documents, any photographs or videos taken by emergency responders, and notes from your initial carrier communications. Having these materials ready allows the professional to immediately identify coverage limits, deductibles, and endorsements that apply to your specific loss. To discover more about our company values and our dedication to helping families recover, visit our corporate portal to read our story. We believe in building a foundation of trust and mutual understanding before any paperwork is signed or submitted.
During the consultation, be prepared to discuss your primary concerns, temporary living arrangements, and any immediate financial pressures you are facing. Your advocate will review your policy declarations page to explain exactly what coverages are available for dwelling repairs, personal property, and loss of use. They will also outline a customized strategy tailored to the unique nature of your fire and smoke damage. If you are ready to take the next step toward securing your rightful settlement, reach out to our team directly via contact us to schedule your initial consultation. Taking this proactive step ensures you have a seasoned professional fighting for your best interests every step of the way.
Frequently Asked Questions
What should I do immediately after a house fire?
Ensure everyone is safe, contact emergency services, secure temporary shelter, and notify your insurance company of the incident. Avoid entering the structurally compromised home until authorized emergency personnel declare it safe for entry.
Why would an insurance company deny a fire damage claim?
Denials can occur due to missed filing deadlines, suspected arson, policy exclusions, or inadequate documentation of the loss. Having a professional advocate helps prevent procedural errors that often trigger unnecessary claim denials.
Can I reopen a fire insurance claim if I already accepted a check?
In many cases, yes, especially if hidden structural or smoke damage is discovered later during the actual restoration process. An experienced claims professional can review your initial settlement to determine if supplemental filings are justified.
How are public adjusters compensated for their services?
Reputable adjusters typically work on a contingency fee basis, taking an agreed-upon percentage of the final insurance settlement payout. This means they only get paid when you successfully recover funds from your insurance carrier.
Do I need to hire an adjuster if my insurance company is cooperative?
Even cooperative insurance companies operate to protect their financial margins rather than maximizing your payout. An independent review ensures you do not overlook hidden damage, code upgrade costs, or full replacement values.
Conclusion
Recovering from a house fire is undoubtedly one of life’s most demanding trials, but you do not have to face the insurance industry alone. Partnering with a qualified fire damage claims adjuster ensures your rights are fiercely protected and your financial recovery is maximized. From uncovering hidden smoke damage to negotiating a fair settlement, professional advocacy takes the heavy burden off your shoulders. Take control of your recovery process today and ensure you receive the full compensation you need to rebuild your home and life.